Payday loan and cash advance apps: the real cost
Money on your phone in five minutes is real. So is an annual cost of several hundred percent.
In short
Payday loans and many cash advance apps look cheap because the fee is small, but on a short loan it adds up to a huge yearly cost: a 15 dollar fee per 100 dollars borrowed for two weeks works out to an APR of almost 400%. A legitimate lender is licensed in your state, shows its fees and APR before you accept, and never asks for an upfront fee. If you are being pressured or threatened, keep records and report it to the CFPB and the FTC.
These apps grew because they solve a real problem: money before payday when the bank will not help. But licensed lenders, fee-based advance apps and outright scams sit side by side in the app store.
What they cost
Payday loan
15 dollars per 100 borrowed
For two weeks, almost 400% APR
Cash advance app
Subscription, express fee or "tip"
Small amounts, but every pay period
Installment loan app
Interest over months
Often well above credit card rates
A small fee repeated every two weeks is the trap. Borrowing 300 dollars every pay period for a year can cost more than the 300 dollars itself.
How to spot a scam
- It asks for a fee before sending the money. Licensed lenders take fees from the loan or at repayment, never upfront.
- It wants access to your contacts or photos.
- It is not licensed in your state, or will not say who the lender is.
- It pressures you to decide right now.
If you are being threatened
- Do not pay out of fear; it rarely stops the pressure.
- Keep screenshots, numbers and receipts.
- Remove the app and revoke its permissions in your phone settings.
- Report it to the Consumer Financial Protection Bureau and the Federal Trade Commission.
If the debt is real and a collector is calling, you have rights about when and how they contact you: debt collectors calling.
Better than an app
The need for fast money almost always comes from having no cushion. A small emergency fund, even one month of expenses, avoids most of these loans: emergency fund. If you already have several, stop the cycle by paying them off one at a time instead of borrowing the next to pay the last.
How it looks in the app
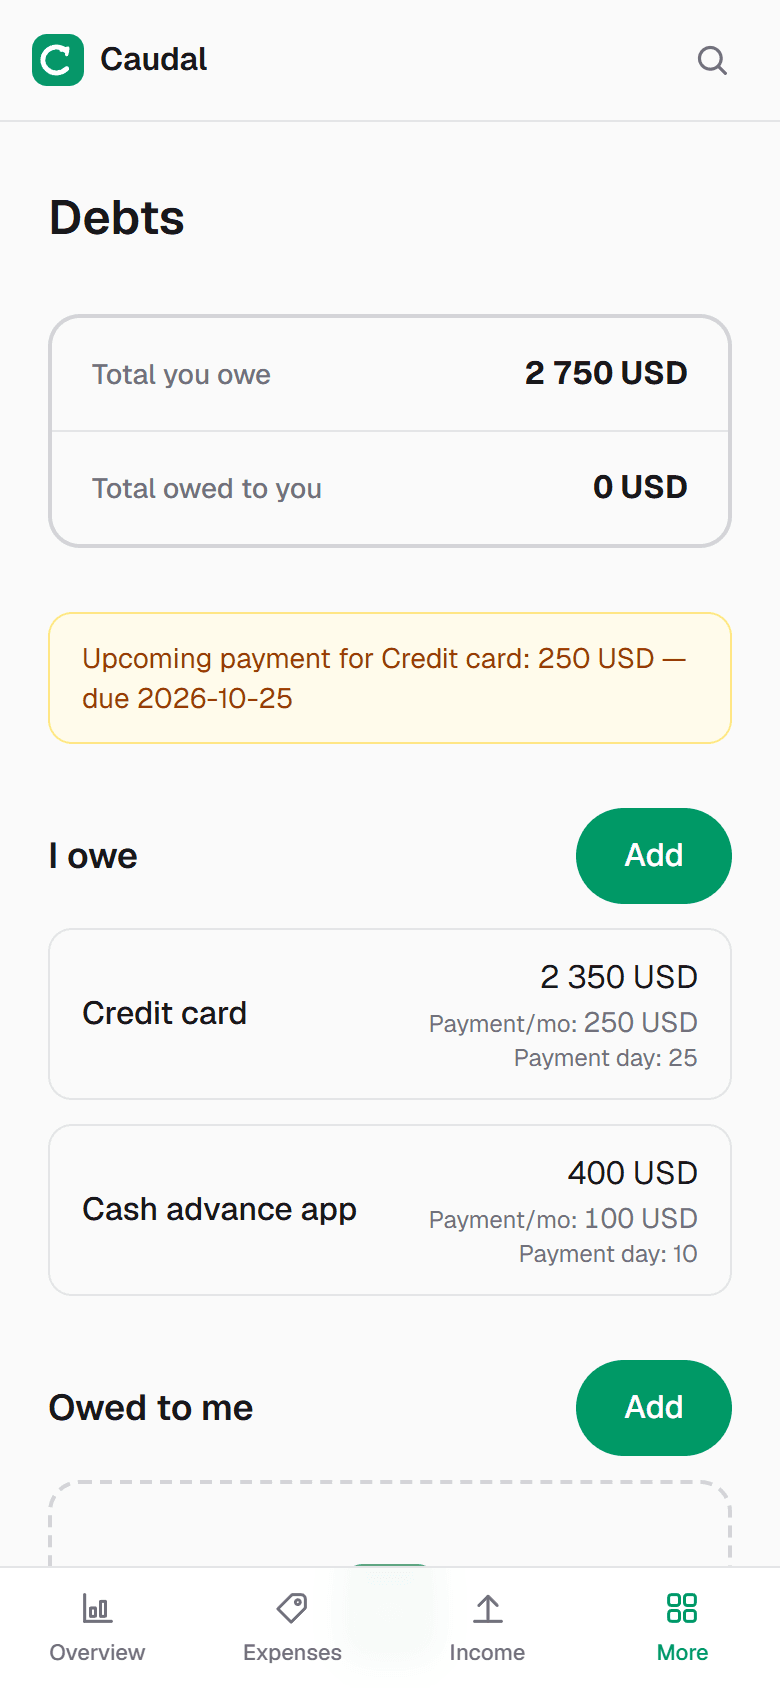
In Caudal you add the advance or the loan as a debt with its due date, next to your card and anything else you owe. Seeing every debt together, with what they take each month, is what helps you not borrow the next one to pay the last.
Common questions
- Are cash advance apps a good idea?
- Once, for a real emergency, they can be cheaper than an overdraft. Used every pay period, the fees add up to a very high yearly cost, and they keep you one paycheck behind.
- How do I know if a loan app is legitimate?
- It is licensed in your state, names the lender, shows the fees and APR before you accept, and never asks for an upfront fee or access to your contacts.
- What is the APR on a payday loan?
- A typical fee of 15 dollars per 100 dollars borrowed for two weeks equals an APR of almost 400%, far above any credit card.
Try it on your own money
Caudal is an expense tracker in Spanish, English and Russian. Several currencies, goals, debts, a shared household budget. Recording an expense takes three seconds.
Start free