Credit card minimum payment: what it really costs
The minimum payment keeps your account in good standing. It does not get you out of debt.
In short
The minimum payment is the smallest amount your card issuer accepts each month, and most of it goes to interest. On a 3,000 dollar balance at 24% APR, paying only the minimum would take about fifteen years and cost almost 4,900 dollars in interest. Paying a fixed 150 dollars a month clears it in about two years for around 870 dollars of interest.
Your statement shows three numbers: the minimum payment, the statement balance and the current balance. The minimum is the smallest of them and by far the most expensive.
How the minimum is set
Issuers use different formulas, but most come down to the month's interest plus about 1% of the balance, with a small floor. Since interest takes most of it, the balance barely moves. And since the minimum is recalculated on a smaller balance each month, it shrinks too: you pay less each month and stay in debt longer.
By law, your statement has to tell you how long paying only the minimum would take. Read that box once; it is usually enough.
Minimum against a fixed payment
Example: a 3,000 dollar balance at 24% APR, no new purchases:
15 years
Minimum payment only
Almost 4,900 dollars in interest
26 months
150 dollars a month, fixed
About 870 dollars in interest
The minimum starts at about 90 dollars in this example. The difference between the two rows is not the rate; it is only how much you pay each month.
How much to pay
- If you can, the statement balance. Then the card costs you nothing.
- If not, a fixed amount above the minimum, the same every month. Do not let the issuer decide your payment.
- Stop using that card while you pay it down. Every new purchase restarts the clock.
With more than one card, pay the minimum on all of them and every extra dollar on the highest APR: how to pay off credit card debt.
When the minimum makes sense
As a safety net in a bad month: a medical bill, a week without work. Paying the minimum once is not a problem; living on it is. If it has been several months, the issue is your budget, not the card: can't pay my loans.
How it looks in the app
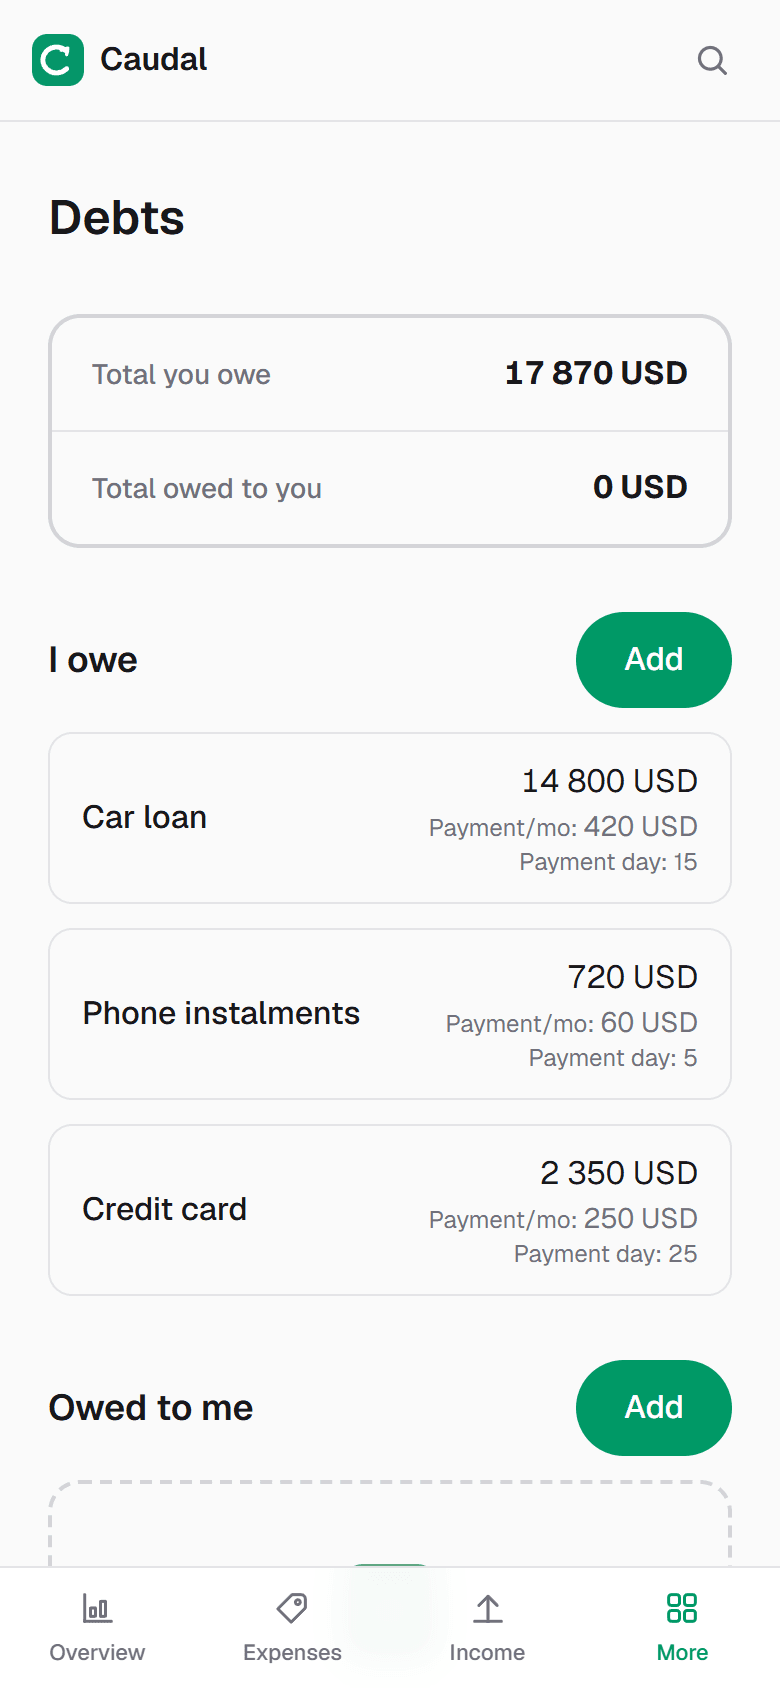
In Caudal you add the card as a debt with the fixed payment you chose, not the minimum. The app reminds you of the due date and counts the payment in your month, so from day one you see what is left after you make it.
Common questions
- What happens if I only pay the minimum on my credit card?
- Your account stays current, but the balance falls very slowly because most of the payment is interest. A 3,000 dollar balance at 24% APR can take around fifteen years to clear this way.
- Is it better to pay the minimum or the statement balance?
- The statement balance, whenever you can, because then you pay no interest. If you cannot, a fixed amount well above the minimum.
- Does paying the minimum hurt my credit score?
- Paying on time helps your score, even if it is the minimum. But a high balance relative to your limit lowers it, so carrying a large balance for years still costs you there too.
Try it on your own money
Caudal is an expense tracker in Spanish, English and Russian. Several currencies, goals, debts, a shared household budget. Recording an expense takes three seconds.
Start free